A free guide from Deanna R. Ngueket, CPA, LLC
Between now and New Year’s Eve I will have this conversation a dozen times. A business owner in Humble, Spring or Atascocita has had a good year, has a quote sitting on the desk for a piece of equipment, and wants to know whether buying it before December 31 will do anything about the tax bill. Usually the question arrives already narrowed: should I take Section 179 or bonus depreciation?
It is a reasonable question and I will answer it below. But in my experience it is the second-most important question in the room. The first one is whether the purchase lands in 2026 at all — and the answer to that has almost nothing to do with the date you pay, or the date you sign, or even the date the truck pulls into your yard.
Here is how I work through it, in the order I actually work through it.
Nothing happens until the property is placed in service
Section 179 lets you expense the cost of qualifying property for the taxable year in which the property is placed in service. Bonus depreciation under section 168(k) works the same way. So the whole calendar question comes down to a term of art, and the term is not “bought.”
Treasury Regulation 1.179-4(e) defines it: placed in service means “the time that property is first placed by the taxpayer in a condition or state of readiness and availability for a specifically assigned function.” Not when you paid for it. Not when the invoice is dated. Not when you first used it.
That cuts in both directions, and most people only hear one of them.
Ready but not used is still placed in service. Publication 946 puts it about as plainly as the IRS ever puts anything: if a machine had been ready for use when it was delivered, it “would be considered placed in service last year even if it was not actually used until this year.” Regulation 1.46-3(d)(2), which the section 179 regulation points to for examples, makes the same point with farm equipment — operational equipment acquired in a year when it is not practicable to use it until the following year is still in a condition and state of readiness. Spare parts set aside to avoid downtime count. So does equipment that is operational but still being tested for defects.
Delivered but not operational is not. The same publication gives the other half: where a machine “was delivered last year” but “was not installed and operational until this year,” it is placed in service this year.
I have seen a lot of money turn on that distinction, and it is almost never in the contract anyone is looking at.
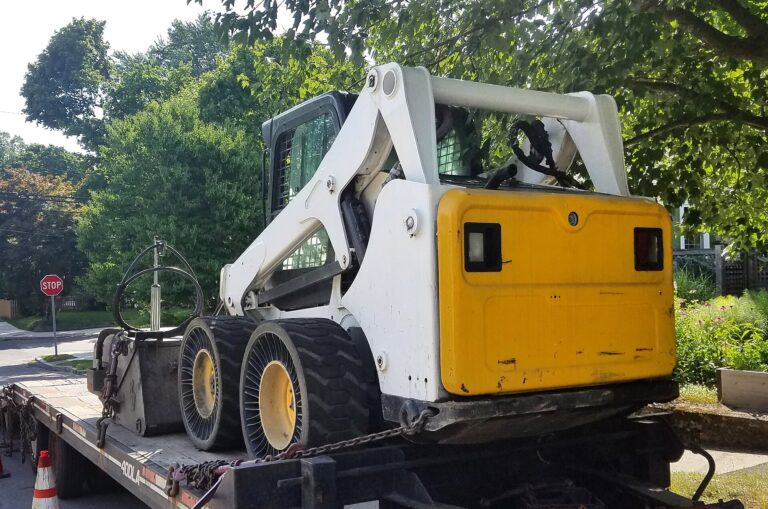
A skid steer, and a two-week difference
Here is a composite of a situation I see every December. A remodeling contractor runs a Schedule C with about $186,000 of profit before any equipment, files single, and buys a used skid steer in December for $94,000, all business use.
Version one. It is delivered December 22 to his yard, fueled, attachments on, ready to work. He has no job for it until January 8. It was in a condition and state of readiness on December 22, so it is placed in service in 2026.
Version two. It comes off the flatbed December 29 without the quick-attach plate, which is on back order. The machine is not operational until January 14. It is placed in service in 2027.
Same machine, same seller, same money, same week. What that two-week difference is worth on his 2026 return:
| Version one (2026) | Version two (2027) | |
|---|---|---|
| Deduction on the 2026 return | $94,000 | $0 |
| Self-employment tax saved | $13,282 | $0 |
| Income tax saved | $15,769 | $0 |
| 2026 federal tax difference | $29,051 | $0 |
That works out to about $309 of 2026 tax per $1,000 of equipment, or an effective 30.9 percent on the purchase.
Two things about those numbers, because a round marginal rate would have been easier and would have been wrong. His self-employment earnings base is $171,771, which is below the 2026 Social Security wage base of $184,500, so the whole deduction comes off at the full 15.3 percent. And the income tax figure is not a flat rate times $94,000: a deduction that size does not stay inside one bracket. It drops him out of the 24 percent bracket into the 22 percent bracket, and it also shrinks his section 199A deduction, because a smaller profit means less qualified business income. The $15,769 is the real difference between the two returns, computed from the 2026 brackets. On a joint return with no other household income the same purchase is worth closer to $243 per $1,000 — which is the first sign that none of this has a universal answer.
I want to be fair about what version two costs him: the deduction is deferred, not destroyed. He gets it in 2027. But if he bought the machine because he was counting on it to handle a 2026 balance due, deferred and destroyed feel identical in April.
What I would actually do. If the purchase is close to year end and the year matters to you, put the readiness date in writing — a delivery receipt, a photo with a timestamp, a signed installation sign-off, a technician’s ticket. The paperwork that proves the purchase is never the paperwork that proves the placed-in-service date, and it is the second one you will be asked for.
Now the actual question: 179 or bonus
Both can get you to a full write-off in year one. In 2026, bonus does it with no election at all, because the One, Big, Beautiful Bill made the 100 percent additional first-year deduction permanent for qualified property acquired and placed in service after January 19, 2025 (Notice 2026-11, announced in IR-2026-06). Section 179 does it by election, up to $2,560,000 for 2026, with that ceiling reduced dollar for dollar once you place more than $4,090,000 of section 179 property in service (Revenue Procedure 2025-32, section 4.24).
Those ceilings are not what separates them for the businesses I work with. Four other things do.
1. Section 179 cannot exceed your business income. Bonus can.
This is the difference that matters most and gets written about least.
Section 179(b)(3)(A) limits the deduction to your taxable income “derived from the active conduct by the taxpayer of any trade or business” for the year, computed without regard to the section 179 deduction itself. Whatever is disallowed carries forward, for an “unlimited number of years” (Regulation 1.179-3(a)).
Section 168(k) has no such limit. Bonus depreciation can take you to a loss.
For an S corporation or a partnership, that income limit is applied twice — once at the entity and once at the owner. Regulation 1.179-2(c)(2) says the limitation “applies to the partnership as well as to each partner,” and Regulation 1.179-2(c)(3) applies the same rules to S corporations and their shareholders. The part that catches people: the amount the entity elects but cannot pass through because of its own income limit carries over at the entity level, and under Regulation 1.179-3(g) the entity may not allocate any of that carryover to its owners until it can deduct it itself.
An HVAC company in Atascocita, and $16,700
Another composite, and one I could describe from several different files. An S corporation with two trucks and a shop buys $140,000 of equipment in 2026 — a sheet metal brake, recovery machines, a shop lift, racking, diagnostic gear. All of it is section 1245 property, none of it is a vehicle, and it is all in service by October. After paying the owner a W-2 salary of $85,000 — a figure set earlier in the year off what the job is worth in this market, not off this decision — the company’s taxable income before depreciation is $40,000. He files jointly; his wife’s salary is $95,000, and that is the household’s only other income.
If he elects section 179 on the whole $140,000: the company’s deduction stops at $40,000. The other $100,000 sits as a carryover on the 1120-S. It is not lost, but it also has no date on it. It waits for a year when the company earns enough to absorb it.
If he lets bonus depreciation run instead: the full $140,000 is deducted, the 1120-S shows a $100,000 ordinary loss, and that loss goes out on his K-1 and against their wages.
| Section 179 route | Bonus route | |
|---|---|---|
| Deducted by the company in 2026 | $40,000 | $140,000 |
| K-1 ordinary income (loss) | $0 | ($100,000) |
| Section 199A deduction | $0 | $0 |
| Taxable income | $147,800 | $47,800 |
| 2026 federal income tax | $21,940 | $5,240 |
| Difference in 2026 tax | $16,700 |
Standard deduction, no other income. Neither route produces a section 199A deduction for 2026: under the first the company’s qualified business income is zero after the $40,000 of section 179, and under the second it is negative.
That is an effective 16.7 percent on the $100,000 — lower than the headline suggests, because the loss carries them out of the 22 percent bracket and well down into the 12 percent one. A deduction is worth the bracket it lands in, and a deduction this size lands in several.
Four conditions have to hold for that loss to be worth $16,700, and I check all four before I say the number out loud:
- Other income to absorb it. A loss is only worth cash if there is income for it to offset. Here the $180,000 of household wages absorbs the whole $100,000. If his wife did not work, most of the loss would simply become a carryforward — which is the very thing the section 179 route was being criticized for.
- Basis. Section 1366(d)(1) limits his losses to his adjusted basis in stock plus any debt the company owes him. Anything beyond that is suspended indefinitely under 1366(d)(2).
- At risk and material participation. Section 465 for the first, section 469 for the second. For an owner who runs the shop every day neither is usually in doubt; for a silent investor, section 469 suspends the loss before any of the rest of this matters.
- Excess business loss. Section 461(l) caps the business loss an individual can use against other income. For 2026 the threshold is $256,000, or $512,000 on a joint return (Revenue Procedure 2025-32, section 4.31). A $100,000 loss is comfortably under it.
There is one more effect worth naming, though it is smaller than it first looks. A negative qualified business income amount is treated as a loss from a qualified trade or business in the next year under section 199A(c)(2), so the $100,000 reduces his 2027 QBI before he gets a 2027 deduction — roughly $20,000 of section 199A deduction, or about $4,400 of tax at a 22 percent rate. But the section 179 route pays the same price, only later: whenever the company finally absorbs that $100,000 carryover, it reduces that year’s qualified business income by the same amount. Bonus does not cost him $4,400. It pulls forward a bill that was coming either way, which is the whole point of the comparison.
One more wrinkle worth knowing, because people reason from it incorrectly. Under Regulation 1.179-2(c)(6)(iv), employees “are considered to be engaged in the active conduct of the trade or business of their employment,” so W-2 wages — including the owner’s own salary — count as taxable income from the active conduct of a trade or business for the section 179 limit. That helps him at his level. It does nothing about the $100,000 stranded at the company level, because the entity limit is applied first.
2. Section 179 is item by item and reversible. The bonus election-out is class-wide and is not.
Section 179 is elected on your return, property by property, specifying the item and how much of its cost you are expensing (section 179(c)(1)). You can revoke that election for a particular item without asking the IRS — though once you revoke, section 179(c)(2) says “such revocation, once made, shall be irrevocable.”
Bonus is the opposite shape. It applies automatically unless you elect out, and the election out under section 168(k)(7) is made “for any class of property.” The instructions for Form 4562 are blunt about what follows: you attach a statement to a timely filed return indicating the class, and “once made, the election cannot be revoked without IRS consent.”
A class is every asset in that recovery period that you placed in service that year. Elect out of bonus for five-year property and you have elected out for the computers you bought in January too.
3. The convention nobody budgets for
Here is where an election made for a sensible reason turns expensive.
If more than 40 percent of the aggregate bases of the property you place in service during the year lands in the last three months, section 168(d)(3) switches you from the half-year convention to the mid-quarter convention — for everything you placed in service that year, not just the December items. A fourth-quarter asset is then treated as placed in service at the midpoint of that quarter: one and a half months of a year.
Two details that matter and are easy to miss. The 40 percent test runs on depreciable basis after any section 179 election — Regulation 1.168(d)-1(b)(4) builds the section 179 reduction into the basis figure — and before any bonus depreciation, which is exactly how the Form 4562 instructions describe it. So your section 179 election is itself a lever on whether the convention applies.
A print shop north of Houston, and a 16-to-1 swing
A third composite. A calendar-year S corporation with a single owner places two pieces of seven-year property in service in 2026: $20,000 of bindery equipment in February, and a $140,000 press on December 10. The company has $310,000 of taxable income before depreciation on these two assets, the owner’s salary is already out of that figure, and he files jointly with his $120,000 salary as the household’s only other income.
Route A — do nothing. Bonus depreciation applies automatically. The whole $160,000 is deducted in 2026. The mid-quarter convention still technically applies — the 40 percent test ignores bonus — but it has no basis left to work on, so it costs him nothing.
Route B — elect out of bonus for seven-year property, on the reasonable theory that much better years are coming in 2027 through 2029 and the deductions will be worth more then.
Now the convention test bites: $140,000 of $160,000 is 87.5 percent in the last three months, so mid-quarter applies. Using the 200 percent declining balance method over a seven-year recovery period (sections 168(b)(1) and 168(c)):
| Basis | Year-one rate | Year-one deduction | |
|---|---|---|---|
| Bindery equipment, February | $20,000 | 25.00% | $5,000 |
| Press, December 10 | $140,000 | 3.57% | $5,000 |
| Total | $160,000 | $10,000 |
A $140,000 press and a $20,000 bindery machine produce the same deduction. The press recovers 3.57 percent of its own basis in year one; the two together recover 6.25 percent. Had the half-year convention applied, the same $160,000 would have produced $22,857 — so the convention by itself accounts for $12,857 of the difference.
| Route A, bonus | Route B, elected out | |
|---|---|---|
| Year-one deduction | $160,000 | $10,000 |
| K-1 ordinary income | $150,000 | $300,000 |
| Section 199A deduction | $30,000 | $60,000 |
| Taxable income | $207,800 | $327,800 |
| 2026 federal income tax | $35,140 | $63,868 |
| Difference in 2026 tax | $28,728 |
Standard deduction, no other income.
A $150,000 swing in deduction produces $28,728 of tax, not the $36,000 a flat 24 percent would suggest, because the section 199A deduction moves in the opposite direction — the bigger his pass-through income, the bigger his 20 percent deduction. That is worth seeing, because it is true of every deduction a pass-through owner takes while the business is still showing a profit: section 199A quietly gives about a fifth of it back. Once a deduction drives qualified business income to zero, as it did in the last example, there is nothing left to give back.
One caveat I would not bury. Route B puts their taxable income before the section 199A deduction at $387,800, within about $15,700 of the 2026 section 199A threshold of $403,500. Past that line the deduction starts to be limited by the company’s W-2 wages, and the whole comparison moves. A spouse’s part-time income or a good December would do it. That is a fair illustration of why I do not hand anyone a rule of thumb here.
None of which makes deferral wrong. The problem is that he chose a 14.29 percent first year and got a 6.25 percent one, and the election that did it cannot be undone without the IRS’s consent. And like the section 179 carryover, this is timing — the basis comes back to him over the remaining seven years. What he spent is the use of $28,728 for several years, plus the risk that his future rates are not what he is counting on.
Could section 179 have fixed the convention? Only on all-or-nothing terms. To pull the fourth-quarter share back under 40 percent he would have to elect section 179 on $126,667 of the press — about 90 percent of it. And the deferral has a real hurdle to clear before it pays: at $327,800 of taxable income he is in the 24 percent bracket, so 2028 has to be enough better to beat 24 cents on the dollar plus the use of the tax he paid early. If it does not clear that hurdle, electing section 179 on the full $160,000 would have been cleaner than electing out of bonus, and is well under the $2,560,000 ceiling. But there is no small version of this fix: either you keep the deferral and accept the mid-quarter convention, or you give the deferral up.
4. Section 179 brings its own recapture. Bonus does not.
If you expense property under section 179 and its business use later drops to 50 percent or less during the recovery period, you recapture the benefit — the excess of what you deducted over what regular depreciation would have allowed goes into income on Form 4797, Part IV, and your basis in the property goes back up by the same amount. Section 179(d)(10) is the hook.
Bonus-depreciated property that is not listed property carries no equivalent trigger. For equipment that sits in a shop this rarely comes up. For anything that could migrate to personal use — a trailer, an ATV, a camera, a laptop — it is a live difference.
The deduction most small businesses should be using and are not
Not everything belongs on a depreciation schedule in the first place.
Regulation 1.263(a)-1(f) gives a de minimis safe harbor: amounts you pay for tangible property can be deducted currently under Regulation 1.162-1 rather than capitalized, if they fall under a per-invoice ceiling. For a business without an applicable financial statement — which is nearly every small business I work with — the ceiling is $2,500 per invoice, or per item as substantiated by the invoice (Notice 2015-82 raised it from $500, effective for taxable years beginning on or after January 1, 2016). With an applicable financial statement, which generally means an audited statement or one filed with the SEC or another federal or state agency, the ceiling is $5,000 and the accounting procedures have to be in writing.
A plumbing company in Humble, and 38 invoices
Two trucks, four employees, and $41,600 of small purchases across 2026 — wrench sets, a jobsite compressor, two laptops, a pipe camera, a shop vacuum, racking — on 38 separate invoices averaging about $1,095. Every one is under $2,500.
With the safe harbor, all of it is deducted when paid. Nothing goes on the fixed asset schedule. There is no section 179 income limit on it, no section 179(d)(10) recapture hook, no basis to track for the rest of a recovery period, and no disposition entry when the compressor dies in 2029.
Two conditions people miss. The amount has to be expensed on your books as well, not capitalized in your accounting software and expensed only on the return — Regulation 1.263(a)-1(f)(1)(ii)(C) requires that you treat it as an expense on your books and records in accordance with your procedures. And paragraph (f)(2) puts inventory, land, and certain rotable and temporary spare parts outside the safe harbor entirely.
In a year with 100 percent bonus available, the first-year dollars often land in the same place, and I will say that plainly rather than oversell this. The value is in what it keeps off your books and what it protects: an expense under section 162 does not depend on bonus depreciation surviving the next tax act.
Here is the catch, and it is the reason this belongs in a fall article rather than an April one. The accounting procedure has to be in place at the beginning of the taxable year. You cannot create one in March 2027 and apply it to 2026. The election itself is annual, made by attaching a statement titled “Section 1.263(a)-1(f) de minimis safe harbor election” to a timely filed original return including extensions, and it is irrevocable for that year.
So for 2026, the procedure either exists already or it does not. For 2027, you have until December 31 of this year.
Also worth knowing, briefly
Used equipment qualifies for both. Section 179(d)(1) requires property “acquired by purchase for use in the active conduct of a trade or business,” and section 179(d)(2) excludes purchases from related parties and property whose basis carries over from the seller. Bonus depreciation has covered used property since 2017, under its own acquisition requirements in section 168(k)(2)(E)(ii), which borrow the same section 179(d) related-party and carryover-basis rules and add one of their own: the property must not have been used by you at any time before you acquired it. If you rented or leased the machine first and then bought it, bonus is off the table — even though the machine is plainly used to everybody else.
Section 179 reaches real property that bonus cannot. Under section 179(d)(1)(B) you can elect to treat “qualified real property” as section 179 property, and section 179(e) defines that to include qualified improvement property plus roofs, heating and air conditioning, fire protection and alarm systems, and security systems installed on nonresidential real property after the building was first placed in service. Sort those two halves, because they do not behave the same way. Qualified improvement property is 15-year property under section 168(e)(3)(E)(vii), so it already gets 100 percent bonus and section 179 adds nothing to it. A new roof or a rooftop HVAC unit on an existing building is 39-year property with no bonus available at all — and there, the section 179 election is the whole deduction. If you re-roofed a warehouse this year, that is a section 179 conversation and only a section 179 conversation.
The order of operations. Section 179 comes off first. The Form 4562 instructions describe the special depreciation allowance as “an additional deduction you can take after any section 179 expense deduction” and “before you figure regular depreciation under MACRS,” and they tell you to reduce the basis you depreciate by the section 179 amount. You are not choosing one or the other on a given asset so much as deciding how much of it to run through each.
Trade-ins. Regulation 1.179-4(d) excludes from “cost” any basis determined by reference to other property you held — so on a trade-in, only the cash difference is section 179 cost.
What I would do between now and December 31
Three things, in this order.
Pull a list of everything you have placed in service in 2026 and everything you still intend to, with the month, and add it up. If more than 40 percent of the basis is landing in October through December, you want to know that before the return rather than during it — and if you are considering electing out of bonus for any class, know that the convention test is waiting on the other side. Leave buildings out of that total: residential rental and nonresidential real property do not count toward the 40 percent test, and neither does anything you placed in service and disposed of in the same year.
For anything arriving in the last two weeks of December, decide which year you want it in and then build the paper for that answer. A machine sitting on a pallet in your shop is not the same as a machine that is ready to run, and neither one looks any different on an invoice.
And if you do not have accounting procedures for small purchases, write them down before January 1. The regulation only requires a business without an applicable financial statement to have the procedures at the start of the year, not to have them in writing — but a procedure you cannot produce on request is a procedure you will have trouble defending.
If you want the long version of how the vehicle rules interact with all of this — they have their own ceilings and their own traps — I wrote about that in October.
Ready to work out what your 2026 equipment purchases actually produce, while you can still do something about it? Call (713) 730-9792 or get in touch. You can also read more about how our proactive tax planning service works, or download one of our free guides.
General information current as of October 2026, not advice for your situation. The worked examples above are composites, and the figures in them depend on filing status, other income and marginal rates that will not match yours. Whether any provision described here applies to you, and what it produces if it does, depends on facts this article cannot know. Deanna R. Ngueket, CPA, LLC – certified public accountant licensed in the State of Texas.